


16 Sep OneDigital vs. Alternatives for Business Insurance
Table of Contents
- Overview: OneDigital and the Business Insurance Brokerage Landscape
- Key Differences in Service Models and Client Support
- Commercial Insurance Coverage Types: What Each Broker Offers
- How to Choose a Commercial Insurance Broker for Your Business
- Risk Management and Specialized Industry Solutions
- Claims Management and Response Times
- Making Your Decision: Which Broker Fits Your Needs
- Frequently Asked Questions
Last Updated: August 14, 2026
Overview: OneDigital and the Business Insurance Brokerage Landscape
A business insurance broker acts as your intermediary with insurance carriers, negotiating coverage terms and helping you navigate complex policy options. Unlike direct insurers, brokers work on your behalf to find solutions tailored to your specific risk profile.
The commercial insurance brokerage market has fragmented significantly over the past decade. Large national firms dominate through scale, but they often treat mid-sized businesses as account numbers rather than partners. This creates an opportunity for specialized brokers and regional agencies that prioritize personalized service and deep industry expertise.
When evaluating a business insurance broker, you’re assessing three things: breadth of carrier relationships (which determines your coverage options), depth of industry knowledge (which determines whether they understand your specific risks), and responsiveness (which determines whether they’re there when you need them). According to the National Association of Insurance Commissioners, brokers licensed across multiple states can access a wider range of carriers and coverage options than single-state operations.
Colstan & Associates brings a family-owned approach to this landscape. As a licensed agency operating across 23+ states with partnerships including Hagerty Insurance for specialized coverage, they combine local service with broader market access. Their client-first model prioritizes personalized service and comprehensive coverage designed to fit your needs and budget.
This comparison examines how different brokers approach commercial insurance differently, where they excel, where they fall short, and how to determine which model fits your business.
Key Differences in Service Models and Client Support
The way a business insurance broker structures client relationships fundamentally shapes your experience. Large national brokers operate on efficiency models: standardized processes, centralized underwriting, and account management through systems. Smaller regional firms prioritize direct relationships: you work with the same agent or small team, and decisions move faster.
Marsh McLennan Agency (MMA) exemplifies the national hybrid model, combining local service with global resources and data-driven insights. This works well for mid-sized businesses needing sophisticated analytics and broad carrier access, though pricing requires direct consultation.
Gallagher operates at an even larger scale, bringing extensive carrier relationships and industry-specific expertise. Their risk management consulting services appeal to businesses with complex exposures, though some customer feedback indicates inconsistency in claims handling responsiveness.
Lockton, the world’s largest independent insurance brokerage, differentiates through independence and creative problem-solving. Because they’re not owned by a larger conglomerate, they claim more flexibility in recommending solutions. Their analytics and catastrophe response services add value beyond basic brokerage.
Colstan & Associates operates from a fundamentally different playbook. As a family-owned agency, they build relationships rather than manage accounts. You work with people who know your business, your history, and your evolving needs. Their client-first approach explicitly prioritizes proactive outreach and personalized service. For standard commercial insurance needs, their focused carrier partnerships often mean faster underwriting and better terms.
Commercial Insurance Coverage Types: What Each Broker Offers
Commercial insurance needs vary dramatically by industry and business size. Core coverage types include general liability, property insurance, workers’ compensation, professional liability, and cyber liability.
General Liability and Property Coverage
All brokers mentioned here can quote general liability and property insurance. The differences emerge in how they assess your risk and what carrier options they present. MMA’s data-driven approach means thorough risk analysis before quoting, which can lead to better-priced policies. Gallagher’s broader carrier network sometimes means access to specialty carriers willing to insure unusual business types.
Colstan & Associates handles standard commercial liability and property through established carrier relationships. Their strength is understanding local market conditions and business-specific risks that national brokers might overlook, translating to faster quotes and coverage that fits your operations.
Industry-Specific Solutions
This is where broker expertise diverges sharply. Restaurant owners, auto repair shops, contractors, and tech companies each face distinct risk profiles that generic commercial policies don’t adequately address.
Gallagher explicitly highlights specialized expertise across various industries. Lockton’s creative problem-solving appeals to businesses with unusual exposures. MMA focuses particularly on healthcare and specialized industries.
Colstan & Associates has direct experience serving auto repair shops, towing companies, and other specialized operators. This means they’ve underwritten dozens of similar businesses, understand specific liability exposures, and know which carriers price competitively for those risks. For a business owner in one of these niches, this experience translates directly to better coverage and faster underwriting decisions.
Employee Benefits and HR Consulting
Larger brokers have built substantial benefits consulting practices. Gallagher and Lockton both offer employee benefits consulting and plan implementation. MMA emphasizes partnerships with national carriers for customized benefit designs.
Colstan & Associates offers employee benefits as part of their commercial package, though their primary strength remains property and casualty insurance. For smaller businesses (under 15 employees) handling benefits through a PEO or standard group plan, this distinction matters less.
Cyber Liability and Data Protection
Cyber liability insurance, covering data breaches, ransomware, and business interruption from cyber events, has become essential. All major brokers now offer this, though depth of coverage options varies. Larger brokers like Gallagher and Lockton have access to specialized cyber carriers and more granular coverage options. Colstan & Associates can quote cyber liability through their carrier partnerships.
| Coverage Type | Colstan & Associates | Marsh McLennan | Gallagher | Lockton |
|---|---|---|---|---|
| General Liability | Yes | Yes | Yes | Yes |
| Property Insurance | Yes | Yes | Yes | Yes |
| Workers’ Compensation | Yes | Yes | Yes | Yes |
| Industry-Specific Solutions | Auto repair, towing | Healthcare focus | Multiple industries | Multiple industries |
| Employee Benefits | Standard | Comprehensive | Comprehensive | Comprehensive |
| Cyber Liability | Yes | Yes | Yes | Yes |
| Risk Management Consulting | Limited | Data-driven | Extensive | Extensive |
How to Choose a Commercial Insurance Broker for Your Business
Choosing a business insurance broker requires evaluating both capability and fit. The wrong choice wastes time and leaves coverage gaps. The right choice becomes a partner in managing your business’s financial risk.
Start by defining your specific needs: primary liability exposures, industry-specific risks, whether you need comprehensive benefits consulting, and whether you operate in one state or multiple states. This clarity determines which brokers are qualified to serve you.
Next, evaluate carrier relationships. Ask each broker: “Which carriers do you work with for my specific business type?” The answer reveals whether they have options or are funneling you toward preferred carriers.
Then assess responsiveness and relationship structure. Will you work with one agent or rotate through a team? How quickly do they respond to emails and calls? What’s their claims process? Ask for references from similar businesses they’ve served for at least two years.
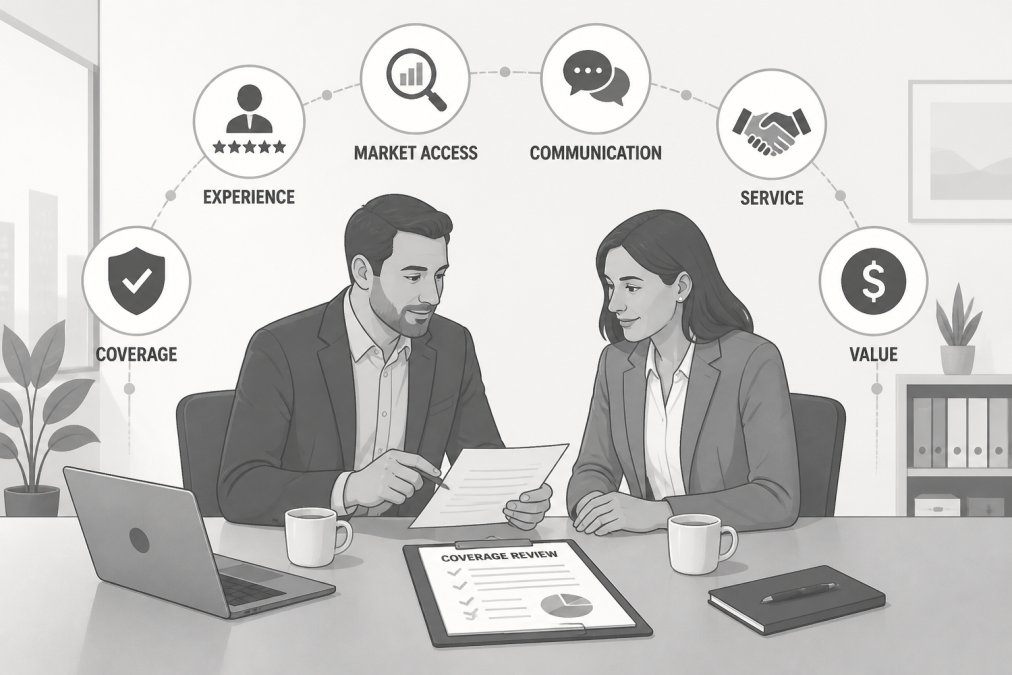
Consider the broker’s proactive approach. The best brokers reach out 90 days before renewal, review your coverage against current operations, and proactively identify gaps or cost savings. Colstan & Associates emphasizes this proactive model explicitly.
Finally, evaluate total cost of ownership, not just premium. Ask each broker: “In the past year, what coverage gaps did you identify for similar businesses? What claims have your clients avoided through your recommendations?” Their specific examples reveal whether they’re actually managing risk or just selling policies.
Risk Management and Specialized Industry Solutions
Proactive risk management separates good brokers from great ones. A risk management approach means identifying vulnerabilities before they become claims, implementing controls to reduce exposure, and structuring insurance efficiently.
Gallagher explicitly positions risk management consulting as a core service. Lockton provides analytics and risk control services beyond basic brokerage. These capabilities appeal to larger businesses with complex risk profiles.
Colstan & Associates approaches risk management through industry-specific expertise. For an auto repair shop, this means understanding common liability exposures, equipment failures, and customer injuries. For a restaurant, it means addressing food safety risks, slip-and-fall hazards, and employment practices liability. This targeted expertise often proves more valuable than generic consulting because it’s rooted in actual experience with your business type.
Interview brokers and ask them to articulate the top three risk exposures specific to your business type. If they struggle to answer, they don’t have real industry expertise. If they identify exposures you hadn’t considered, they’re thinking like a risk manager.
Claims Management and Response Times
When you file a claim, response time and clarity become everything. A slow broker means days of uncertainty about coverage and claim status. A responsive broker provides answers within hours.
Gallagher’s size creates a risk here, with some customer reviews noting delays in claims handling. Lockton’s independence theoretically allows faster decision-making, though scale can still introduce delays.
Colstan & Associates’ family-owned model typically means faster claims handling because decisions don’t require approval from multiple layers. You work with people who know your policy and business, which accelerates claim resolution.
Ask potential brokers directly: “What’s your average response time to claims inquiries? Can you provide a specific example of a claim you handled for a similar business?” Their specific answers matter more than generic service promises.
Making Your Decision: Which Broker Fits Your Needs
The right broker depends on your business size, industry, and service expectations.
Choose a national broker like Gallagher or Lockton if: You’re a larger business (50+ employees) with complex, multi-state operations. You need sophisticated risk consulting and benefits management. You operate in an industry requiring specialized expertise they’ve developed. You value access to dozens of carriers and exotic coverage options.
Choose Colstan & Associates if: You’re a small to mid-sized business (under 50 employees) in a standard commercial sector or one of their specialty niches (auto repair, towing, restaurants). You value personalized service and proactive relationship management. You want faster underwriting and claims handling. You prefer working with the same agent over time. You want a broker who actually knows your business and your local market.
Choose MMA if: You’re a mid-sized business seeking data-driven risk analysis. You value a hybrid model combining local service with national resources. You’re in healthcare or another specialized sector where they’ve built expertise.
The fundamental decision is between scale and relationship. National brokers offer breadth; regional brokers offer depth. Both have merit; the choice depends on which you actually need.
Choosing the right business insurance broker determines whether your coverage protects your actual business or just checks boxes. Colstan & Associates brings 20+ years of industry experience, licensed agents across 23+ states, and partnerships including Hagerty Insurance for specialized coverage. Their client-first approach means proactive outreach, personalized service, and coverage designed to fit your specific needs and budget. Start a quote with Colstan & Associates and experience the difference between transactional brokerage and genuine risk partnership.
Frequently Asked Questions
What makes OneDigital different from other business insurance brokers?
OneDigital combines digital tools with personalized service, offering tailored coverage for businesses across various industries. Unlike purely online platforms, OneDigital provides dedicated agents who understand your specific business risks. Their approach focuses on proactive risk management and customized solutions rather than one-size-fits-all policies. The key differentiator is their ability to blend technology with human expertise to deliver both efficiency and personalization.
How do I know which commercial insurance broker is right for my business?
When choosing a commercial insurance broker, evaluate their experience with your industry, the range of coverage options they offer, their claims response times, and whether they provide proactive policy reviews. Ask about their risk management consulting services and how they handle renewals. Check if they integrate with your existing HR or payroll software. A strong broker should understand your specific business exposure and offer tailored solutions, not generic packages.
What commercial insurance coverage types should a small business have?
Most small businesses need general liability to cover bodily injury and property damage claims, property insurance for physical assets, workers’ compensation if you have employees, and professional liability if you provide services. Depending on your industry, you may also need cyber liability, employment practices liability, or specialized coverage. A qualified insurance broker can assess your specific business risks and recommend appropriate coverage to protect your assets and minimize exposure.
How quickly do insurance brokers typically respond to claims?
Response times vary significantly between brokers. Larger national brokers may take 10-20+ days to provide initial updates, while mid-sized and regional brokers often respond within 2-5 business days. Your broker should have a dedicated claims team and clear communication protocols. When selecting a broker, ask about their average claims response time and whether they provide real-time claim status updates. Fast, transparent claims handling directly impacts your business during critical situations.
This article was written using GrandRanker