


16 Sep Custom Insurance for High Net Worth: A 2026 Guide
Table of Contents
- What Is Custom Insurance for High Net Worth?
- Key Differences Between Standard and High-Value Policies
- Umbrella Insurance for High Net Worth: Extended Liability Protection
- Agreed Value vs Actual Cash Value Insurance: Which Protects Your Assets?
- High-Value Home Insurance Requirements and Coverage Options
- Protecting Valuable Collections and Specialized Assets
- Assessing Your Insurance Needs and Building a Tailored Strategy
- Conclusion
Last Updated: August 27, 2026
What Is Custom Insurance for High Net Worth?
Custom insurance for high net worth is a tailored approach to protecting significant personal assets and wealth through policies designed specifically for your financial situation. Rather than applying standard homeowners or liability coverage, this specialized protection accounts for the unique risks that come with valuable collections, multiple properties, and substantial net worth.
At Colstan & Associates, we’ve worked with high net worth individuals who discovered that off-the-shelf policies left critical gaps in their coverage. A standard homeowners policy might cover your primary residence up to a certain limit, but what happens when that limit falls short of your home’s actual replacement cost (iii.org)? What protects your art collection, your vintage automobiles, or your jewelry when they exceed standard policy thresholds? This is where custom insurance for high net worth becomes essential.
The real value lies in moving beyond generic coverage limits. High net worth individuals face exposure that typical policies simply weren’t designed to handle. You need asset protection strategies that recognize the complexity of your situation, whether that’s a portfolio of properties, specialized collections, or significant liability exposure from your lifestyle and activities.
Key Differences Between Standard and High-Value Policies
Standard homeowners insurance applies a one-size-fits-all approach. Your policy has predetermined coverage limits, standard deductibles, and exclusions that don’t account for your specific circumstances. These policies work well for average-value homes and typical possessions, but they break down when your assets exceed the policy’s maximum coverage.
High-value policies operate on entirely different principles. They begin with a comprehensive assessment of what you actually own and what those items would cost to replace. Rather than capping coverage at a fixed amount, these policies are built around your actual asset values.
Consider the practical differences:
| Aspect | Standard Policy | High-Value Policy |
|---|---|---|
| Coverage assessment | Generic limits applied uniformly | Custom valuation of each asset |
| Replacement cost | Actual cash value (depreciated) | Agreed value (pre-negotiated) |
| Deductible options | Fixed, limited choices | Flexible, customizable |
| Special items coverage | Limited or excluded | Specifically included with appraisals |
| Claims process | Standard timeline | Priority handling with dedicated adjuster |
The agreed value approach matters significantly. With a standard policy, if your home burns down, the insurer calculates what it would cost to rebuild using current construction costs, but they may dispute that figure. With custom insurance for high net worth, you and your insurer agree upfront on the replacement cost. When a claim occurs, there’s no negotiation about value. You already settled that.
Another critical difference is the flexibility in deductible structures. A high net worth individual might choose a higher deductible on their primary residence because they have the financial capacity to absorb that cost, allowing them to reduce their premium and redirect those savings toward protecting more specialized assets.
Umbrella Insurance for High Net Worth: Extended Liability Protection
Umbrella insurance sits above your standard liability coverage, providing additional protection when claims exceed your underlying policy limits. For high net worth individuals, this layer becomes increasingly important because your assets make you a more attractive lawsuit target.
Think about it practically: if someone is injured on your property and sues for damages, a standard homeowners policy might provide $300,000 in liability coverage. If the judgment exceeds that amount, your personal assets become vulnerable. Umbrella coverage for high net worth typically starts at $1 million and extends upward, depending on your risk profile and asset base (iii.org).
The protection extends beyond your home. Umbrella insurance covers liability claims arising from your personal activities, hosting events, operating a boat, driving a vehicle, anywhere your underlying policies might have gaps or insufficient limits. This is particularly valuable if you’re involved in activities that carry higher risk exposure.
Many high net worth individuals pair umbrella insurance with specific risk management strategies. If you host frequent gatherings, your umbrella policy becomes essential protection. If you own recreational property or operate vehicles beyond standard use, the extended liability becomes critical. Colstan & Associates helps clients structure umbrella coverage that aligns with their actual lifestyle and activities, not just theoretical risks.
The cost of umbrella insurance is often surprisingly modest relative to the protection it provides. The premium reflects the reality that most claims never reach umbrella limits, the underlying policies handle the majority of incidents. You’re essentially paying for catastrophic protection against the scenario where a major claim exhausts your primary coverage.
Agreed Value vs Actual Cash Value Insurance: Which Protects Your Assets?
This distinction fundamentally changes how claims are settled and how well your assets are actually protected. Understanding the difference is essential for anyone considering custom insurance for high net worth.
Actual cash value means the insurer calculates what your property is worth at the time of loss, accounting for depreciation. A five-year-old roof, a used vehicle, or older furnishings are worth less than they were when new. If your home has a $500,000 actual cash value policy and it burns down, the insurer determines the current depreciated value and pays that amount. You’re responsible for any gap between that payout and actual reconstruction costs.
Agreed value flips this approach. Before any loss occurs, you and your insurer agree on what your property is worth. You provide documentation, appraisals, photos, detailed inventories, and establish a value together. When a claim happens, the insurer pays that pre-agreed amount without depreciation calculations or disputes about current value.
For high net worth individuals, agreed value is almost always the better choice. Here’s why: reconstruction costs have increased substantially. Labor, materials, and specialized construction for high-end homes far exceed what depreciation-based calculations would provide. By locking in an agreed value upfront, you eliminate the risk that actual reconstruction costs will exceed your payout.
This matters especially for custom homes, historic properties, or homes with specialized features. A standard actual cash value calculation might not account for the specific materials, craftsmanship, or architectural details that define your property. Agreed value policies let you specify these details and ensure adequate coverage.
The same principle applies to valuable collections. An art collection’s value isn’t determined by depreciation, it may appreciate significantly over time (peer-reviewed research). Agreed value policies for fine art, jewelry, wine, or other collectibles are structured around professional appraisals that establish the current fair market value. When you file a claim, you receive that appraised value.
High-Value Home Insurance Requirements and Coverage Options
Insuring a high-value home requires a different underwriting process than standard homeowners insurance. Insurers need detailed information about your property’s construction, condition, systems, and specific features. This isn’t bureaucratic overhead, it’s how they accurately price the risk and ensure adequate coverage limits.
Most high-value home policies require a professional appraisal or inspection before coverage begins. The insurer wants to understand the home’s construction quality, the age and condition of major systems (roof, foundation, electrical, plumbing, HVAC), and any special features that affect replacement cost. This rigor ensures your coverage is accurate and adequate.
Coverage options expand significantly with high-value policies. Beyond the basic dwelling coverage, you can add:
- Replacement cost coverage for building materials and labor
- Agreed value for contents covering furnishings, art, and personal property
- Loss of use coverage that extends beyond standard policies if your home becomes uninhabitable
- Increased liability limits reflecting the risk profile of your property and activities
- Water damage and flood protection tailored to your specific location and exposure
- Specialty coverage for pools, guest houses, outbuildings, or other structures
The underwriting process for custom insurance for high net worth is more thorough because the stakes are higher. An insurer covering a $2 million home needs to understand exactly what they’re protecting and what it would cost to rebuild. This rigor actually works in your favor, it ensures your coverage is accurate and adequate. tax planning strategies.
Some insurers also offer enhanced service features as part of high-value policies. These might include 24/7 claims support, dedicated claim adjusters, or preferred contractor networks that specialize in high-end restoration. When you have a significant loss, these services can make the recovery process smoother and faster.
Protecting Valuable Collections and Specialized Assets
Standard homeowners insurance typically limits coverage on specific items. Jewelry might be capped at $2,500. Fine art at $5,000. Firearms at $3,000. If you own valuable collections that exceed these limits, you need specialized coverage specifically designed for those assets.
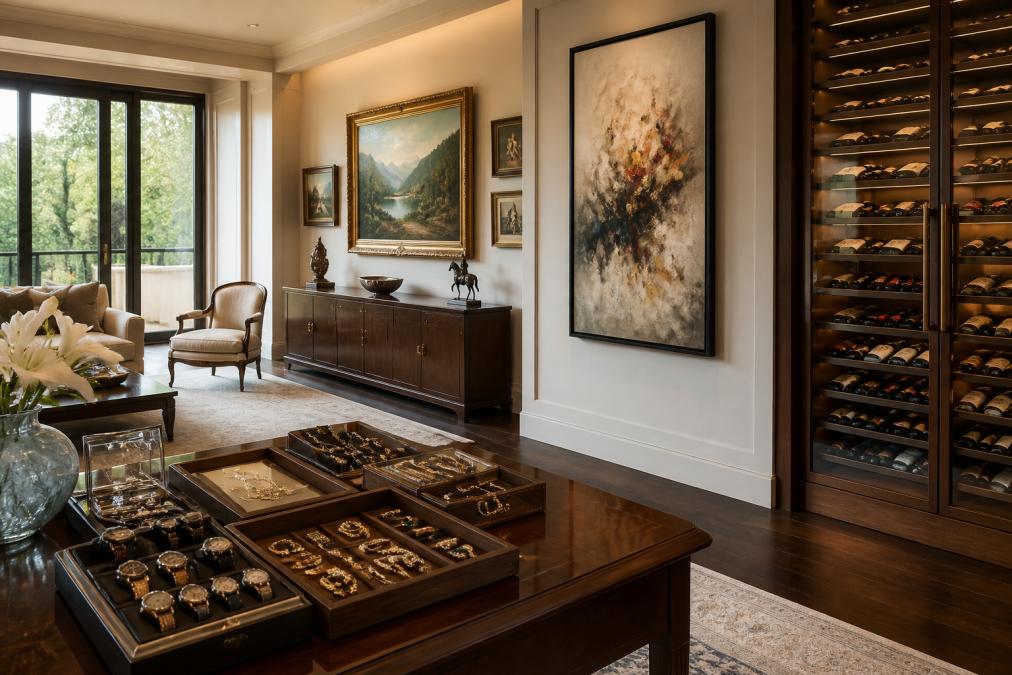
Fine art requires a different approach entirely. An insurance company can’t simply assign a value to your painting, they need professional appraisal documentation. This appraisal establishes the fair market value and becomes the basis for your coverage limit. If you acquire new pieces, the policy can be adjusted with updated appraisals. This protects you if the artwork appreciates significantly between appraisals.
Jewelry and watches follow a similar pattern. A valuable watch collection or engagement ring with significant sentimental and monetary value needs specific coverage with appraisals. Standard homeowners policies won’t adequately protect these items.
Wine collections present unique challenges. Beyond the monetary value, wine requires specific storage conditions to maintain its value. A high-value wine policy accounts for both the collection’s value and the infrastructure required to protect it, climate control, security, proper storage conditions. The policy recognizes that improper storage damages the asset, so it may include coverage for losses resulting from storage failures.
Rare automobiles, whether classic cars or specialty vehicles, require specialized coverage beyond standard auto insurance. Colstan & Associates partners with specialized carriers like Hagerty Insurance to provide coverage that accounts for the unique value and usage patterns of classic and collector vehicles. These policies understand that a 1967 Mustang isn’t driven the same way as a daily commuter.
Collectible firearms, rare books, vintage instruments, and other specialized assets all benefit from dedicated coverage. The key is having detailed documentation, appraisals, photographs, condition reports, that establishes value and allows for proper coverage limits.
Assessing Your Insurance Needs and Building a Tailored Strategy
Determining adequate coverage requires honest assessment of your assets, your lifestyle, and your risk exposure. This isn’t a quick questionnaire, it’s a comprehensive review.
Start by cataloging your assets. This means documenting everything of significant value: your primary residence and any secondary properties, vehicles, collections, jewelry, art, and other valuables. For each item, you need current value, either through professional appraisal, recent purchase documentation, or fair market value assessment.
Next, evaluate your liability exposure. Do you host frequent gatherings? Own a pool or trampoline? Drive recreational vehicles? Operate a business from your home? Have a history of lawsuits or significant claims? Each of these factors affects the liability coverage you need.
Consider your risk tolerance and financial situation. Some high net worth individuals choose higher deductibles because they can absorb those costs themselves. Others prefer lower deductibles for peace of mind. There’s no universal right answer, it depends on your circumstances and preferences.
Think about coverage gaps in your current insurance. Many people discover that their existing policies don’t adequately cover specific assets or situations. A comprehensive review often reveals these gaps before a loss occurs.
Document everything. Photographs, appraisals, purchase receipts, and detailed descriptions create the foundation for accurate coverage and smooth claims. This documentation is invaluable if you ever need to file a claim.
Finally, establish a review schedule. Your insurance needs change as your assets change, as your property ages, and as your lifestyle evolves. Annual reviews with your insurance agent ensure your coverage remains adequate.
Protecting substantial wealth requires more than standard insurance policies. Custom insurance for high net worth addresses the specific risks that come with significant assets, valuable collections, and complex financial situations. At Colstan & Associates, we’ve spent over 20 years helping high net worth individuals build comprehensive protection strategies tailored to their unique circumstances. Our team understands the nuances of agreed value coverage, umbrella protection, and specialized asset insurance. We work with you to identify gaps in your current coverage, structure policies that actually protect what you’ve built, and ensure you’re not overpaying for unnecessary coverage. Start a conversation about your insurance needs today, we’ll help you build a strategy that matches your actual risk profile and asset base.
Frequently Asked Questions
What distinguishes custom insurance for high net worth from standard homeowners insurance?
Custom insurance for high net worth provides higher coverage limits, agreed value protection, and specialized underwriting tailored to luxury assets. Standard policies use actual cash value, lower limits, and generic coverage that doesn't account for fine art, jewelry, or estate-level exposures. High net worth policies also include excess liability and claims advocacy, services designed for complex asset portfolios that standard policies simply don't address.
Why would I need umbrella insurance for high net worth if I have homeowners coverage?
Umbrella insurance for high net worth extends your liability protection far beyond standard homeowners limits. If someone is injured on your property or you're found liable for significant damages, your homeowners policy may only cover $300,000-$500,000. Umbrella coverage sits above that, protecting assets from lawsuits that exceed your base policy. For high net worth individuals, this is essential risk mitigation because a single claim could threaten years of wealth accumulation.
What's the difference between agreed value and actual cash value insurance?
Agreed value insurance sets a predetermined replacement cost for your assets before a loss occurs, you and your insurer agree on the value upfront. Actual cash value pays only what the item is worth at the time of loss, minus depreciation. For luxury homes and fine art, agreed value is superior because it eliminates depreciation disputes and ensures you're fully compensated. Most high net worth policies use agreed value to protect against underinsurance and settlement delays.
How do I know if my home qualifies as a high-value home for insurance purposes?
High-value home insurance requirements typically apply to homes with replacement costs exceeding $500,000-$1,000,000, depending on your location and insurer. Factors include square footage, construction quality, location, and the value of built-in features. If your home has luxury finishes, custom architecture, or sits in a high-cost area, you likely need specialized coverage. Colstan & Associates can assess your specific property and recommend the right high-value home insurance requirements for your situation.
This article was written using GrandRanker