


16 Sep High Net Worth Asset Protection Strategies: A Complete Guide
Table of Contents
- Understanding Asset Protection for High Net Worth Individuals
- Umbrella Insurance for High Net Worth Individuals
- Trust-Based Asset Protection Strategies
- Limited Liability Company Asset Protection Benefits
- Fraudulent Transfer Laws and Asset Protection Planning
- Digital Asset Protection for High Net Worth Individuals
- Estate Planning and Tax-Efficient Wealth Transfer
- Implementing a Customized Asset Protection Plan
- Frequently Asked Questions
Last Updated: August 3, 2026
When it comes to protecting significant wealth, high net worth asset protection strategies are essential. At Colstan & Associates, we’ve worked with many affluent individuals who discovered too late that having wealth and protecting it are two entirely different challenges. According to Federal Reserve data on wealth concentration, the top 1% of Americans hold approximately 32% of all wealth, yet many lack comprehensive protection frameworks. This guide covers the legal structures, insurance solutions, and planning approaches that shield assets from creditors, litigation, and other threats to your financial security.
Understanding Asset Protection for High Net Worth Individuals
Asset protection differs fundamentally from wealth management or investment strategy. It’s about preventing loss, not creating gain. For high net worth individuals, the stakes are higher because so is the target on your back.
Why Asset Protection Matters at Higher Wealth Levels
The wealthier you are, the more attractive you become to litigation. Professional liability, business disputes, personal injury claims, and divorce proceedings all escalate in scope when significant assets are involved. A single lawsuit can threaten decades of wealth accumulation if your assets sit unprotected in your personal name.
High net worth individuals face unique exposure across multiple properties, businesses, investment portfolios, and valuable collections. Courts scrutinize asset transfers made after a lawsuit is filed or threatened. Legitimate protection strategies implemented during calm periods, when no claims are pending, hold up under legal challenge. This is why high net worth asset protection strategies work best when established proactively, years before any crisis emerges.
Common Legal Threats to Wealth
Business ownership creates the most obvious exposure. If you operate a company, a single accident or claim can expose your personal assets if the business structure doesn’t shield them properly. Personal liability extends beyond business, automobile accidents, property injuries, and employment disputes all create exposure. Divorce and family disputes represent a category many high net worth individuals underestimate, as assets are scrutinized intensely and aggressive attorneys work to pierce corporate veils. Professional liability is particularly acute for doctors, lawyers, engineers, and financial advisors, where malpractice claims can exceed business insurance and target personal assets.
Umbrella Insurance for High Net Worth Individuals
Umbrella insurance sits at the foundation of most high net worth asset protection strategies because it’s affordable, straightforward, and immediately effective. Think of it as a safety net that catches liability claims exceeding your underlying insurance limits.
Coverage Limits and Policy Structure
Umbrella policies typically start at $1 million in coverage and extend upward to $5 million, $10 million, or more. The cost is surprisingly reasonable, $1 million in umbrella coverage often runs $150-$300 annually for individuals with clean driving records. As coverage increases, the per-million cost typically decreases.
The structure works like this: your homeowners insurance covers the first $300,000 in liability, and your umbrella policy kicks in for anything above that amount, up to its limit. If you’re sued for $2 million in damages, your homeowners policy pays its limit, and the umbrella covers the remaining $1.7 million (assuming you carry a $1 million umbrella).
Umbrella policies require you to maintain minimum underlying coverage on your home, auto, and other insurable assets. Most carriers require homeowners limits of at least $300,000 and auto limits of $250,000/$500,000.
Most high net worth individuals underestimate their umbrella needs. A $1 million umbrella is a starting point, not a destination. If your net worth exceeds $2 million, a $2 million umbrella minimum makes sense. For net worth above $5 million, consider $5 million or higher. The additional premium is modest compared to the gap it closes.
When to Layer Umbrella Coverage
For truly high net worth individuals with net worth exceeding $10 million, layering multiple umbrellas provides continuous coverage. The first umbrella might be $5 million, with a second umbrella covering $5-10 million above it. This creates seamless protection without gaps. You can also layer umbrellas across different carriers, ensuring that a dispute with one carrier doesn’t leave you exposed.
Trust-Based Asset Protection Strategies
Trusts are the workhorses of estate planning, but they also serve critical asset protection functions. The right trust structure can shield assets from creditors while maintaining your control and flexibility.
Irrevocable Trusts and Creditor Protection
An irrevocable trust transfers assets out of your personal name into a trust entity. Once assets are in the trust, they’re no longer your property, they belong to the trust. This separation is powerful for creditor protection because creditors can’t seize what you don’t legally own.
The tradeoff is control. In a true irrevocable trust, you surrender the ability to modify the trust terms or reclaim the assets. This permanence is precisely what makes creditors respect it. Many high net worth individuals use irrevocable life insurance trusts (ILITs) for dual benefits, the trust owns your life insurance policy, removing the death benefit from your taxable estate while protecting the policy from creditors. Qualified personal residence trusts (QPRTs) allow you to transfer your home into the trust while retaining the right to live there for a specified period, after which it passes to beneficiaries with creditor protection during the trust period.
Irrevocable trusts provide the strongest creditor protection available in most states, but they require careful planning because you can’t easily undo them. Work with an estate planning attorney to ensure the trust structure aligns with your long-term goals.
Domestic Asset Protection Trust States
Some states have created legal frameworks specifically designed to protect assets from creditors. Domestic asset protection trusts (DAPTs) in states like Nevada, South Dakota, Delaware, and Alaska allow you to transfer assets into a trust while retaining some control and flexibility, something irrevocable trusts don’t permit.
You establish a trust under the laws of a favorable state, transfer assets into it, and designate yourself as a discretionary beneficiary. The trust document gives the trustee authority to distribute income and principal to you at the trustee’s discretion. Creditors can’t force the trustee to distribute funds to satisfy a judgment, so your assets remain protected. Timing matters significantly, establish DAPTs during calm periods, ideally 2-3 years before any foreseeable litigation.
| Strategy | Control Level | Creditor Protection | Flexibility | Best For |
|---|---|---|---|---|
| Irrevocable Trust | Low | Very Strong | Minimal | Permanent wealth preservation |
| DAPT | Moderate | Strong | Moderate | Flexibility with protection |
| Revocable Trust | High | Minimal | Maximum | Estate planning without creditor shield |
Limited Liability Company Asset Protection Benefits
Limited Liability Companies (LLCs) separate personal liability from business liability. When you operate a business as an LLC, the company is a separate legal entity. If the business is sued, the judgment applies to the company’s assets, not your personal assets. Your home, investment portfolio, and other personal property remain protected.
Liability Isolation and Personal Asset Shielding
The key requirement is maintaining the LLC as a separate entity. This means keeping business and personal finances separate, maintaining proper business records, paying yourself a reasonable salary, and following corporate formalities. If you comingle funds, ignore corporate procedures, or use the LLC as a personal piggy bank, courts may disregard the LLC structure and hold you personally liable, a process called piercing the corporate veil.
Multi-Layer LLC Structures for Complex Portfolios
High net worth individuals with diverse assets often use multiple LLCs to isolate different types of risk. Each property, business, or investment category gets its own LLC. If a tenant is injured in Property A (held by LLC-A) and wins a $500,000 judgment, that judgment applies only to LLC-A’s assets. Your other properties in separate LLCs, your business, and your investment portfolio remain untouched.
Fraudulent Transfer Laws and Asset Protection Planning
Asset protection strategies must navigate fraudulent transfer laws. These laws exist to prevent debtors from hiding assets to avoid paying creditors. If you’re solvent, have no creditors, and transfer assets to a trust or LLC during calm periods, courts view this as legitimate planning. If you transfer assets after a lawsuit is filed or threatened, courts are much more skeptical.
Most states follow the Uniform Fraudulent Transfer Act (UFTA) or its successor, the Uniform Voidable Transactions Act (UVTA). These laws provide safe harbors for legitimate planning. If you establish trusts, LLCs, and other structures during periods of financial stability, with proper documentation, and for legitimate business or estate planning purposes, courts generally uphold them.
Transferring assets with the specific intent to avoid paying a known creditor is fraudulent, even if you technically remain solvent. Courts scrutinize transfers made after litigation is threatened or filed. Establish asset protection structures during calm periods, ideally years before any foreseeable claims.
Digital Asset Protection for High Net Worth Individuals
Digital assets represent an increasingly significant portion of high net worth portfolios, yet they’re often overlooked in traditional asset protection planning.
Cryptocurrency and Digital Wealth Security
Cryptocurrency holdings face unique risks. They’re valuable, portable, and difficult to trace. Cold storage, holding cryptocurrency in offline wallets not connected to the internet, is the baseline security measure. Hardware wallets like Ledger and Trezor store private keys offline, making them inaccessible to hackers. Multi-signature wallets require multiple private keys to authorize transactions, adding another layer of protection. For creditor protection, some high net worth individuals establish cryptocurrency holdings through trusts or LLCs, where the legal entity holds the cryptocurrency rather than you personally.
Cybersecurity Measures for Financial Accounts
Multi-factor authentication (MFA) is essential for every financial account. Using unique, complex passwords for each account prevents a breach at one institution from compromising others. Password managers like 1Password, LastPass, and Bitwarden generate and store secure passwords, making this manageable. Create a comprehensive digital asset inventory stored securely, ensuring executors and heirs can locate and access your digital wealth if something happens to you.
Estate Planning and Tax-Efficient Wealth Transfer
Asset protection and estate planning are deeply intertwined. The structures that protect assets during your lifetime also facilitate efficient wealth transfer to your heirs.
Minimizing Estate Tax Exposure
Federal estate taxes apply to estates exceeding $13.61 million (2026 threshold). Above this amount, the federal government claims 40% of the excess. Lifetime gifting allows you to transfer up to $18,000 per recipient annually without gift tax consequences. Over time, this removes substantial assets from your taxable estate. Irrevocable life insurance trusts (ILITs) remove life insurance proceeds from your taxable estate. The ILIT owns the policy, you pay premiums through annual gifts to the trust, and when you die, the proceeds pass to beneficiaries outside your taxable estate. Grantor retained annuity trusts (GRATs) allow you to transfer appreciating assets to heirs while retaining an income stream, with remaining assets passing to heirs tax-free if you survive the term.
Coordinating Asset Protection with Succession Planning
Your asset protection structure should align with your succession plan. For business owners, establishing the business as an LLC with succession provisions in the operating agreement facilitates smooth transition upon your death. For real estate portfolios, holding properties through separate LLCs allows you to transfer ownership of individual LLCs to heirs without disrupting other properties. A revocable living trust holds assets during your lifetime, avoids probate upon your death, and specifies how assets transfer to heirs.
Implementing a Customized Asset Protection Plan
Generic advice doesn’t work for high net worth asset protection strategies because your situation is unique. Your risk profile, asset composition, family structure, and goals all influence which strategies make sense.
Assessing Your Risk Profile and Exposure
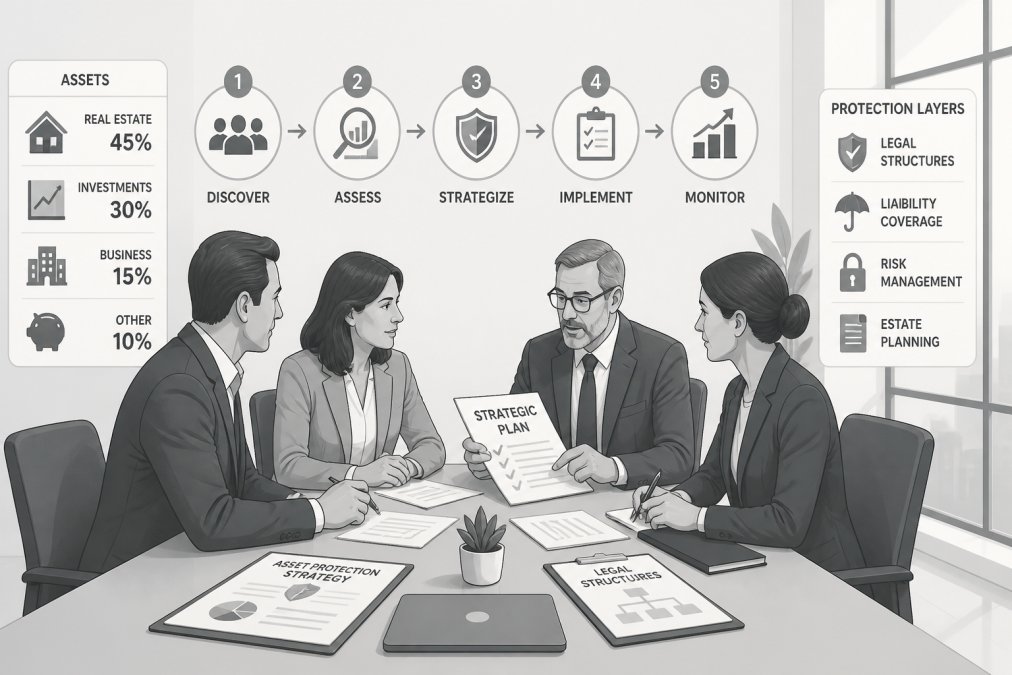
Begin by identifying your specific risks. Are you a business owner? What type of business, and what liability does it create? Do you own real estate? Your profession matters, doctors, lawyers, and engineers face professional liability. Your asset composition influences planning. If 80% of your net worth is real estate, real estate-specific strategies deserve emphasis. Your family situation affects planning, including concerns about creditors targeting family members or divorce risk.
Coordinating Insurance, Legal Structures, and Professional Guidance
Effective asset protection coordinates multiple layers. Insurance provides the first layer, umbrella policies catch claims before they threaten personal assets. Legal structures provide the second layer, with LLCs, trusts, and business entities separating liability and preventing creditors from reaching protected assets.
Start with insurance. Establish adequate umbrella coverage based on your net worth and risk profile. If your net worth is $3 million, a $3 million umbrella minimum makes sense. Establish appropriate legal structures, if you own business, operate it through an LLC; if you own real estate, consider holding it through LLCs; if you have substantial liquid assets, consider a trust structure. Coordinate with tax planning to ensure your asset protection strategy doesn’t create unexpected tax liability. Document everything to show that your business and personal finances are separate and that structures were established for legitimate planning purposes. Review and update regularly as your circumstances change and your net worth grows.
High net worth asset protection requires proactive planning, professional guidance, and a commitment to maintaining structures properly. At Colstan & Associates, we work with high net worth clients to coordinate insurance, legal structures, and professional guidance into cohesive asset protection plans. Our client-first approach means we take time to understand your specific situation, identify your unique risks, and recommend strategies tailored to your circumstances. If you’ve built significant wealth and haven’t yet implemented comprehensive asset protection, now is the time to act. Reach out to Colstan & Associates today to get started with a personalized assessment of your asset protection needs.
Frequently Asked Questions
What is the best way to protect high net worth assets from creditors and lawsuits?
The most effective approach combines multiple layers: umbrella liability insurance, properly structured legal entities like LLCs or irrevocable trusts, and diversified asset placement. Umbrella policies extend protection beyond standard homeowners or auto coverage. Irrevocable trusts remove assets from your personal ownership, shielding them from creditor claims. For business owners, LLCs and family limited partnerships create liability barriers. The right strategy depends on your specific exposure, asset composition, and jurisdiction. Consult with an attorney specializing in asset protection to design a plan aligned with your situation.
How do irrevocable trusts protect assets from lawsuits?
Irrevocable trusts remove assets from your personal estate, making them legally unavailable to satisfy personal judgments or creditor claims. Once transferred into the trust, you no longer own the assets, so they cannot be seized. Creditors cannot reach trust assets because they belong to the trust entity, not to you individually. However, timing matters significantly. Transfers made after a lawsuit is filed or threatened may be challenged as fraudulent conveyances under state law. Assets must be placed in the trust well before any legal exposure arises to ensure protection. Consult a qualified attorney to ensure your trust structure complies with your state’s laws.
Can an LLC protect my personal assets from business liability?
Yes, an LLC provides liability isolation between business operations and personal assets. If the business faces a lawsuit or creditor claim, your personal property, home, and savings are generally protected. The LLC’s assets are available to satisfy business obligations, but creditors cannot pursue your individual assets. This separation is called the corporate veil or liability shield. However, protection is not absolute. Piercing the veil is possible if you fail to maintain proper business practices, commingle personal and business funds, or engage in fraud. For maximum protection, maintain separate bank accounts, follow LLC formalities, carry adequate business insurance, and keep detailed records. Many high net worth individuals use multiple LLCs to further segregate risk across different business ventures or asset categories.
What are fraudulent transfer laws and how do they affect asset protection planning?
Fraudulent transfer laws, governed by the Uniform Fraudulent Transfer Act (UFTA) in most states, prevent transfers made to avoid paying creditors. If you transfer assets to a trust or other entity while insolvent or when a creditor claim is imminent, a court may reverse the transfer and make those assets available to satisfy the judgment. The key distinction is timing and intent. Legitimate asset protection involves transferring assets during peaceful times, before any legal threat emerges. Courts examine whether you received fair value, your financial condition at the time of transfer, and whether you concealed the transfer. Proper planning requires establishing protection strategies years before potential litigation, maintaining business records, and ensuring all transfers are documented and made for legitimate reasons beyond creditor avoidance.
At what net worth level should I implement formal asset protection strategies?
Asset protection becomes increasingly important as your net worth grows, typically when you have significant assets, real estate holdings, or operate a business with liability exposure. Many professionals recommend beginning formal planning once you accumulate $500,000 to $1 million in assets, though the right threshold depends on your specific situation. Factors include your profession (doctors, contractors, and business owners face higher litigation risk), your liability insurance coverage gaps, the value of your primary residence, and your jurisdiction’s creditor protection laws. Even modest wealth benefits from basic protection like umbrella insurance and proper business structuring. Rather than a specific dollar figure, consider your exposure level and the consequences of losing assets to a lawsuit. Proactive planning is far less expensive than defending against creditors after an event occurs.
How do umbrella insurance policies work for high net worth individuals?
Umbrella insurance provides additional liability coverage above the limits of your underlying homeowners, auto, and business policies. A typical umbrella policy starts at $1 million and can extend to $5 million or more. It activates only after your underlying policies are exhausted. For example, if your homeowners policy has a $300,000 liability limit and you face a $1.5 million judgment, your homeowners policy covers the first $300,000, and umbrella coverage pays the remaining $1.2 million (minus any deductible). Umbrella policies are cost-effective, typically running $150 to $300 annually per million dollars of coverage. However, they require that underlying policies meet minimum standards and that you maintain appropriate coverage elsewhere. High net worth individuals often carry multiple umbrella layers and ensure coordination with other asset protection strategies like trusts and LLCs.
What role does cybersecurity play in protecting digital assets and financial accounts?
Cybersecurity is critical for protecting high net worth individuals from fraud, identity theft, and unauthorized access to digital assets and financial accounts. Threats include hacking, phishing, social engineering, and malware targeting cryptocurrency wallets, brokerage accounts, and bank access. Implement multi-factor authentication on all financial accounts, use strong unique passwords managed by a password manager, enable account alerts, and regularly monitor statements for unauthorized activity. For cryptocurrency and digital assets, consider hardware wallets that store private keys offline, reducing hacking risk. Work with your financial advisor and attorney to document digital asset locations and access procedures in your estate plan. Many high net worth individuals employ cybersecurity professionals to audit their digital security posture and implement additional protections like VPNs and encrypted communication channels.
This article was written using GrandRanker