


16 Sep Is Classic Car Insurance Worth It for Daily Drivers in 2026?
Table of Contents
- The Real Question: Can You Daily Drive a Classic Car?
- Classic Car Insurance Mileage Limits: The Hard Numbers
- Agreed Value vs Actual Cash Value Insurance: What’s Protected?
- The Daily Driver Dilemma: What Happens When You Commute?
- Standard Auto Insurance for Vintage Vehicles: The Cost Comparison
- The Risks Insurers Won’t Tell You: Wear and Tear and Safety Gaps
- How to Make the Right Call for Your 2026 Driving Habits
- Conclusion: The Verdict on Daily Driving Your Classic
- Frequently Asked Questions
Last Updated: September 9, 2026
The idea of driving your vintage vehicle every day is appealing, but the insurance reality is more complicated than most enthusiasts expect. Classic car insurance is designed for occasional use, weekend cruising, and car shows, not stop-and-go commutes. Before you rely on your collector car as a daily driver, you need to understand how the policy language, mileage limits, and claims process actually work. At Colstan & Associates, we help classic car owners weigh these trade-offs regularly, and the answer almost always comes down to one question: how often will you really drive it?
The short answer is that classic car insurance is rarely worth it for true daily drivers. The policies that offer the best protection for collector vehicles, including agreed value coverage, come with usage restrictions that daily commuting violates. If you drive your classic car to work every day, you may face claim denials or find yourself paying for coverage that doesn’t apply when you need it most. Below, we’ll break down the mileage limits, coverage types, and hidden risks so you can make an informed decision for 2026.
The Real Question: Can You Daily Drive a Classic Car?
Technically, yes, you can drive a classic car every day. The mechanical reality, however, is that daily commuting introduces wear, tear, and accident risk that collector car policies are not designed to cover. Classic car insurance is a specialty product built around a specific usage profile: limited annual mileage, secure storage, and a primary vehicle for everyday transportation.
Most specialty insurers underwrite based on the assumption that your classic is an excess vehicle, not your main mode of transport. That distinction matters because it shapes every part of the policy, from the premium calculation to the claims process. If your situation matches that profile, classic car insurance delivers meaningful savings. If it does not, you are exposing yourself to coverage gaps that a standard auto policy would handle more reliably.
Classic Car Insurance Mileage Limits: The Hard Numbers
Mileage restrictions are the single biggest constraint on daily driving a classic car. Most specialty policies cap annual mileage between 2,500 and 7,500 miles, with the most common limits falling in the 3,000 to 5,000-mile range. These caps are not arbitrary; they are actuarial benchmarks that assume the vehicle is used for pleasure, car shows, and occasional weekend trips, not for the 12,000 to 15,000 miles a typical commuter racks up annually.
The mechanism of enforcement is where many owners get caught off guard. Insurers do not install GPS trackers on most classic cars, but they do review odometer readings at each policy renewal. A vehicle that was insured for 4,000 annual miles but shows 12,000 miles on its odometer at the first renewal is a red flag that triggers an underwriting review. The insurer can then require a usage-based telematics device, reclassify the vehicle to a higher-risk tier, or non-renew the policy outright.
Beyond the annual cap, the more restrictive provision is often the ‘pleasure use only’ clause. This language explicitly prohibits using the vehicle for commuting to work or school, even if you stay under the annual mileage limit. A 10-mile round-trip commute five days a week adds roughly 2,600 miles per year, which might fit within a 5,000-mile annual cap. But the policy language does not care about the math; it cares about the purpose. Commuting is a disqualifying use, regardless of the odometer.
Watch Out
A common pattern is for owners to underestimate their annual mileage by 20-30% when applying for a policy. If your commute is 20 miles round-trip, that alone is 5,000 miles per year before you drive anywhere on the weekend. Insurers can and do deny claims when they discover a vehicle is being used for regular commuting, citing the ‘pleasure use only’ clause.
Some specialty insurers offer ‘occasional commuting’ endorsements that allow limited commuter use, typically capped at 2,500 miles per year or 30 days per year. These endorsements cost more and still assume the vehicle is not your primary transportation. If you drive your classic to work more than once or twice a week, even these flexible endorsements are a poor fit. The honest benchmark is simple: if your commute alone pushes you past 50% of the annual mileage limit, a classic car policy is the wrong fit. A standard auto policy, while more expensive, will not penalize you for the miles you actually drive or the purpose of your trips.
Agreed Value vs Actual Cash Value Insurance: What’s Protected?
The most valuable feature of classic car insurance is agreed value coverage, which is the difference between protecting your investment and watching it depreciate. Actual cash value, by contrast, factors in depreciation, which can leave you far short of what it costs to replace your vintage vehicle.
For a collector car that has appreciated or undergone restoration, agreed value is essential. The trade-off is that agreed value coverage comes with the usage restrictions discussed earlier.
The Daily Driver Dilemma: What Happens When You Commute?
When you commute in a classic car, you introduce risks that the policy was never priced for. Daily driving means more time on the road, more exposure to accidents, and more wear on components that are expensive to replace. Insurers underwrite classic car policies based on low-risk usage, and daily commuting flips that risk assessment entirely.
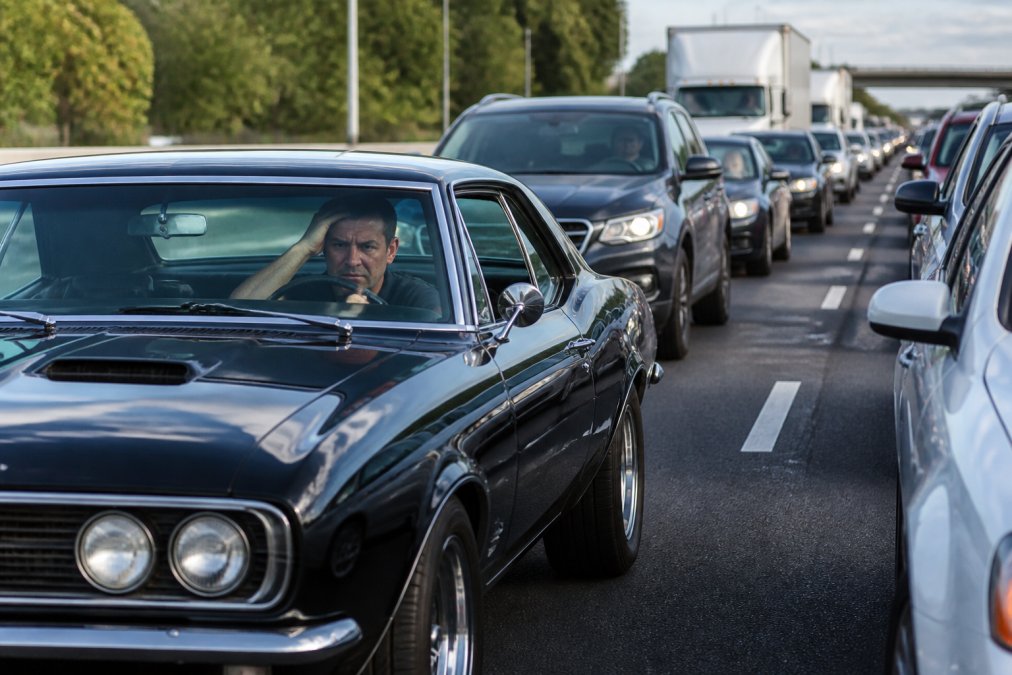
The claims process is where the problem surfaces. If you file a claim during a morning commute, the insurer may investigate whether you were using the vehicle in a way that violates the policy terms. A pattern of daily commuting can be grounds for denying coverage entirely. That leaves you paying out of pocket for repairs to a vehicle that is often more expensive to fix than a modern car.
Using a classic car for daily commuting can void your collector policy. If the insurer determines the vehicle is your primary transportation, they can deny your claim and cancel the policy, leaving you without financial protection at the moment you need it most.
::: windshield repair coverage.
Standard Auto Insurance for Vintage Vehicles: The Cost Comparison
Standard auto insurance for a vintage vehicle is usually more expensive, but it offers something classic car policies do not: unrestricted daily use. A standard auto policy does not care whether you drive five miles or fifty miles a day, and it covers your classic car the same way it covers any other vehicle. The cost difference reflects that flexibility.
| Coverage Type | Mileage Restrictions | Total Loss Payout | Best For |
|---|---|---|---|
| Classic Car Policy | Annual limits, no daily commuting | Agreed value | Occasional weekend driving |
| Standard Auto Policy | No usage restrictions | Actual cash value | Daily drivers and commuters |
| Hybrid/Modified Policy | Varies by insurer | Depends on endorsements | Limited daily use with collector status |
Those savings exist precisely because the insurer assumes you are not commuting. If you need a vehicle for daily transportation, the honest comparison is between a standard policy on your classic and a standard policy on a modern daily driver. The classic will likely cost more to insure, repair, and maintain.
The Risks Insurers Won’t Tell You: Wear and Tear and Safety Gaps
If your engine fails during a commute, that is a maintenance issue, not an insured loss. The same applies to suspension components, brake rotors, and clutch assemblies that wear out faster under daily stop-and-go driving. Insurers explicitly exclude ‘mechanical or electrical breakdown’ and ‘wear and tear’ from collector policies, meaning a daily-driven classic that needs a $4,000 transmission rebuild after a year of commuting is entirely on your dime.
Start Quote →
There is also a secondary market consequence that daily drivers rarely consider: the ‘facility’ or high-risk insurance market. This is a hidden financial penalty that compounds the original problem. A daily-driven classic that loses its collector policy can end up costing more to insure than a brand-new luxury sedan, once you factor in the high-risk market premium and the cost of repairing a vintage vehicle after a commute-related accident.
The practical takeaway is that daily driving a classic is not just an insurance mismatch; it is a safety and liability decision. The cheapest classic car policy is not worth it if it does not cover how you actually drive, and the safety gap is a risk that no policy can offset. Daily commuting demands a standard auto policy, even if it costs more, because the alternative is a denied claim, an unsafe vehicle, and a potential high-risk market penalty.
How to Make the Right Call for Your 2026 Driving Habits
Start by being honest about your driving patterns. If your classic car is a weekend toy that stays garaged during the workweek, classic car insurance with agreed value is the right choice. If you find yourself reaching for the keys on weekday mornings, you need a standard auto policy that covers daily use without mileage restrictions.
For owners who want both, consider a hybrid approach: keep the classic on a collector policy for weekend enjoyment, and use a separate, modern vehicle for commuting. That protects your investment while keeping your daily transportation practical and safe. The Insurance Information Institute’s guide to auto insurance recommends matching your coverage to actual usage, not sentimental attachment.
This is where working with an experienced agency pays off. At Colstan & Associates, we partner with Hagerty Insurance to place classic car coverage for collectors, and we also handle standard auto policies for daily drivers. Our licensed agents can review your driving habits and recommend the coverage structure that actually fits.
Conclusion: The Verdict on Daily Driving Your Classic
Classic car insurance is worth it for owners who treat their vehicle as a collector piece, not a commuter. The agreed value protection and premium savings are real, but they are conditional on limited, hobbyist use. If you need to drive your classic every day, a standard auto policy is the honest choice, even though it costs more and pays out less in a total loss.
The decision comes down to protecting your financial investment versus protecting yourself on the road. Colstan & Associates can help you sort through both options, whether that means securing agreed value coverage through our Hagerty partnership or finding the right standard auto policy for daily use. Start a quote with Colstan & Associates and get coverage that matches how you actually drive.
Frequently Asked Questions
Will Hagerty or other specialty insurers cover a daily driver?
Most specialty insurers like Hagerty, Grundy, and American Collectors will not cover a vehicle used as a daily driver. Their underwriting guidelines require a separate primary vehicle for regular commuting and errands. The classic car must be for weekend use, car shows, and pleasure driving only. If you use a classic for daily commuting, you risk having a claim denied or the policy canceled. You would need to look at standard auto insurance for vintage vehicles instead, or keep your classic on a specialty policy and buy a separate daily driver.
What are the typical mileage restrictions for classic car insurance policies?
Classic car insurance mileage limits vary by provider but typically range from 2,500 to 7,500 miles per year. Some policies, like those from Grundy, offer unlimited mileage options, but they still prohibit daily commuting. The restrictions exist because the risk assessment is based on the vehicle being a weekend or pleasure vehicle, not a primary mode of transport. Exceeding these limits can void your coverage.
How does agreed value coverage differ from actual cash value?
Actual cash value (ACV) pays the market value at the time of the loss, which accounts for depreciation. For a classic car that is appreciating, agreed value is usually the better choice. With ACV, you may only receive a fraction of what it would cost to replace your vintage vehicle. This distinction is why agreed value vs actual cash value insurance is the most important decision for classic car owners.
Is it more expensive to insure a classic car than a standard car?
No, classic car insurance is often significantly cheaper than a standard auto policy. Specialty insurers can offer premium savings of 30% to 50% compared to a daily driver policy. However, this assumes you meet the usage restrictions. If you drive the car daily, the risk profile changes, and you will not qualify for these lower rates. You would then need to price a standard auto insurance policy for vintage vehicles, which is usually more expensive due to higher replacement costs.
What happens if I file a claim while using my classic car for commuting?
If you file a claim while using a classic car for daily commuting, and your policy has a usage restriction that prohibits it, the insurer can deny your claim. If you need to drive your classic to work regularly, talk to a licensed agent about a policy that permits that usage, or consider a standard auto policy.